
Air Bike Landed Cost Calculator | China Manufacturer Direct Pricing
Most importers think freight is the biggest cost. The real margin killer hides in Manila port fees, 12% VAT stacking, and misclassified HS codes.
The true landed cost of an air bike into the Philippines equals CIF value plus customs duty (typically 5–15% under AHTN for fitness equipment), plus 12% VAT calculated on CIF plus duty, plus PPA port surcharges (arrastre, wharfage, ISPS, CFS if applicable), plus customs broker fees, plus inland delivery. These add-ons can push final cost 25–40% above CIF, and customs valuation uses BOC reference pricing—not your invoice. [NEED_CITE: Philippines BOC customs valuation rules based on transaction value vs. reference price]
I spent years watching night-shift container roll-outs at Qingdao’s Huangdao port before switching to trade. One shipment of commercial treadmills bound for Dubai taught me the hard way: we declared it as a full container, but the client needed LCL clearance, and the box was mixed with another buyer’s kettlebells and plates. The destination agent froze everything. Demurrage climbed daily. The deconsolidation bill alone ate a chunk of profit that could have covered return freight. That’s when I realized landed cost is never just FOB plus ocean freight. Clearance codes, destination port surcharges, mixed-container declaration traps—miss one, and your margin disappears. Now, before I quote any client, I break down every post-arrival cost line by line.
Let me walk you through exactly what goes into the calculation, where importers get blindsided, and how to estimate it properly before you place a production order.
What Exactly Goes Into the Landed Cost of an Air Bike in the Philippines?
Landed cost is not a single number—it is a stack of sequential calculations, each with its own logic and trigger point.
The formula runs like this: product cost (FOB) plus freight plus insurance equals CIF. Then CIF becomes the base for customs duty. Duty gets added to CIF, and that combined figure becomes the base for 12% VAT. On top of that sit port charges levied by PPA and terminal operators, customs broker service fees, document processing fees, and finally inland trucking from the port to your warehouse or gym floor. [NEED_CITE: Philippines AHTN tariff structure for fitness and exercise equipment categories]
Each layer compounds. VAT does not apply to the invoice price alone—it applies to CIF plus duty. Port charges are not bundled into freight—they are separate line items billed by the arrastre operator, the wharfage authority, and the terminal. Broker fees vary by shipment complexity. And inland delivery depends on whether your destination is Metro Manila, Cebu, or a provincial gym two hours from the port.
A Southeast Asian distributor once ordered a 40HQ mixed with commercial treadmills and air bikes for multiple gym clients. The container arrived in Manila, and because the goods were destined for different end-users, the client requested deconsolidation and split delivery at the port. The deconsolidation surcharge, re-handling fees, and separate trucking runs for each sub-shipment added a significant percentage on top of the original per-unit freight allocation. Nobody had budgeted for it. [NEED_CITE: PPA port surcharge structure for deconsolidation and split delivery at Manila International Container Terminal]
The lesson: if you only calculate FOB plus freight, you are pricing a fantasy.
How Do You Determine the Correct HS Code and Duty Rate?
Misclassifying your air bike under the wrong AHTN code triggers penalties, delays, and sometimes a full customs revaluation—and the duty rate difference between headings can be substantial.
Commercial air bikes fall under exercise equipment headings in the ASEAN Harmonized Tariff Nomenclature. The specific subheading determines whether your MFN duty rate sits at the lower end or the higher end of the fitness equipment range. Getting this wrong does not just mean overpaying—it means the Bureau of Customs can flag your shipment for examination, reassess the value, and impose surcharges. [NEED_CITE: AHTN code classification for commercial exercise bikes and fitness equipment under Philippines tariff schedule]
I have seen importers declare air bikes under general machinery headings instead of specific exercise equipment codes because their broker assumed it would simplify paperwork. The result: customs flagged the mismatch, held the container for physical inspection, and the client paid daily storage fees while the classification was corrected. The inspection cycle stretched across multiple working days, and demurrage accumulated with each passing day. [NEED_CITE: BOC customs examination and reclassification procedures for misdeclared fitness equipment]
The correct approach is to request the manufacturer’s recommended HS code based on the product’s technical specifications—resistance type, frame construction, intended commercial or home use—and cross-reference it with the current AHTN schedule before the goods leave the factory. At Bick, we provide pre-classification support for every container we ship, matching each SKU to its proper AHTN heading so the broker at destination has no ambiguity when filing the import declaration. This is especially critical when a single container carries multiple product categories.
What Hidden Port and Clearance Fees Catch Importers Off Guard?
Arrastre, wharfage, CFS charges, ISPS fees, and broker service charges are almost never included in the supplier’s CIF quote—yet they routinely inflate the final landed cost by a noticeable margin.
When a supplier quotes CIF Manila, that figure covers product cost, ocean freight, and marine insurance. It does not cover the terminal handling charges billed by the Philippine Ports Authority and the arrastre operator once the container touches the wharf. It does not cover the International Ship and Port Facility Security fee. It does not cover the customs broker’s professional fee, the documentary stamp tax, or the processing charges for the import clearance. [NEED_CITE: PPA terminal handling charges and arrastre fee schedule for Manila and Cebu ports]
A gym owner in Cebu imported his first commercial air bike shipment directly from China. He budgeted based on the CIF price plus an estimate for duty and VAT. What he did not account for were the terminal storage fees that began accruing after the free period expired, the arrastre charges for moving the container from vessel to yard, the wharfage dues, and the broker’s release fee. By the time the goods reached his facility, the total port-side costs represented a significant percentage of the original CIF value—far more than he had projected. The cash flow gap nearly stalled his gym opening. [NEED_CITE: Philippines customs clearance fee structure including arrastre, wharfage, and broker charges]
The fix is simple but rarely done: before production begins, ask your customs broker at destination for a full fee schedule applicable to your shipment type (FCL or LCL), product category, and destination port. Build those figures into your cost model. Do not assume the supplier’s freight forwarder has included them—they have not.
How Can You Avoid Costly Mistakes in Mixed-Container Shipments?
When a single container holds multiple product categories—say air bikes, treadmills, plate-loaded machines, and free weights—each SKU must be declared separately with its own HS code, value allocation, and duty calculation. Missing one line item can hold the entire container.
This is where many importers learn the hardest lesson. A mixed container is not one shipment—it is dozens of individual declarations bundled into a single box. Customs requires line-by-line reporting: each product type, its quantity, its allocated value, its HS code, and its corresponding duty and VAT. If one item is omitted or misdeclared, the entire container gets flagged. The correction process requires amended documents, re-examination, and additional broker fees. Meanwhile, demurrage accumulates daily. [NEED_CITE: Philippines BOC requirements for line-by-line declaration in mixed-container fitness equipment shipments]
I have worked with gym distributors who ordered complete turnkey packages—cardio zone, strength zone, free weight zone—all in one container to save on freight. The concept makes sense logistically. But at the declaration stage, every single machine type needs its own entry. A functional trainer, a cable crossover, a smith machine, a set of dumbbells, and an air bike are not one product. They are five separate declarations with five different HS codes and potentially five different duty rates.
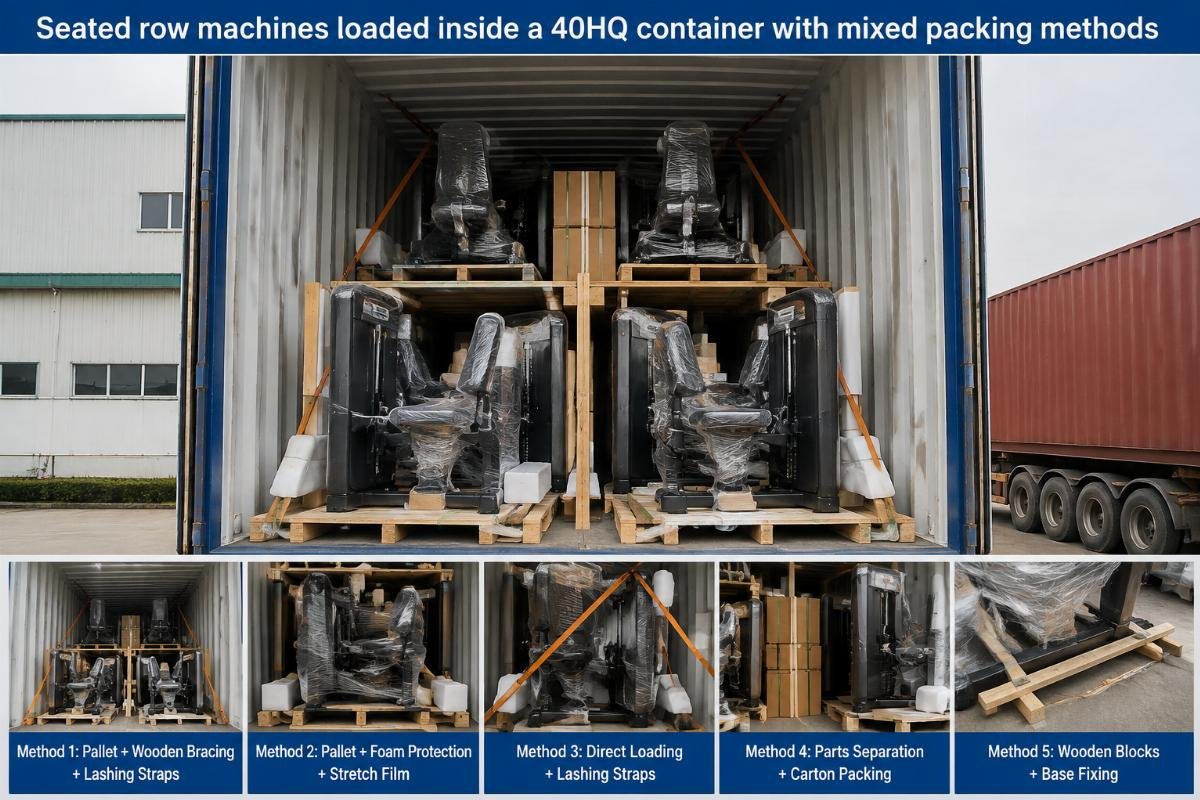
Bick handles container-load consolidation for full gym packages across multiple regions. When we load a mixed container—treadmills alongside air bikes alongside plate-loaded equipment—our documentation team prepares a complete packing list and commercial invoice that allocates value to every SKU by category. The broker at destination receives a declaration-ready document set, not a guess. This pre-clearance preparation eliminates the most common cause of mixed-container holds: incomplete or mismatched line-item reporting. [NEED_CITE: Best practices for mixed-container fitness equipment documentation and customs declaration]
What Practical Steps Can You Take to Estimate Landed Cost Accurately Before Ordering?
Request a full cost breakdown from your supplier and your destination broker before production starts—including CIF, estimated duty, VAT calculation basis, port charges, and inland delivery—so there are no surprises when the container arrives.
The process works in four stages:
First, obtain the supplier’s FOB price and confirm the product specifications, quantities, and container loading plan. This determines the freight basis and whether you are shipping FCL or LCL.
Second, ask the supplier’s freight forwarder for a CIF quote to your destination port. Verify what is included—marine insurance coverage, transit time, and whether the quote covers origin-side documentation fees. [NEED_CITE: Standard CIF quotation components for fitness equipment shipments from China to Southeast Asia]
Third, engage your destination customs broker and provide the commercial invoice, packing list, and product descriptions. Request a written estimate of duty (based on the confirmed HS codes), VAT (calculated on CIF plus duty), port charges (arrastre, wharfage, ISPS, terminal handling), broker service fees, and inland trucking to your final destination. This is the step most importers skip—and it is the step that prevents cash flow shocks.
Fourth, add the supplier’s inland delivery cost if the goods are being shipped from the factory to the port of loading, and any origin-side inspection or certification fees if applicable.
The sum of all these elements is your true landed cost per unit. Compare that figure against your intended selling price or project budget before you commit to production. If the margin does not work at this stage, no amount of negotiation on freight will fix it—you need to renegotiate product cost or adjust your pricing model.
Conclusion
Landed cost calculation for air bikes into the Philippines is a multi-layer exercise that extends far beyond CIF—duty, VAT, port surcharges, and broker fees compound on top of each other, and mixed-container shipments demand line-by-line declaration precision.
Build your cost model before production, not after the vessel sails. Confirm HS codes with your broker, request a full destination fee schedule, and ensure your supplier provides SKU-level documentation for every item in the container. The difference between a profitable import and a cash flow crisis is not the product price—it is the accuracy of your landed cost calculation.